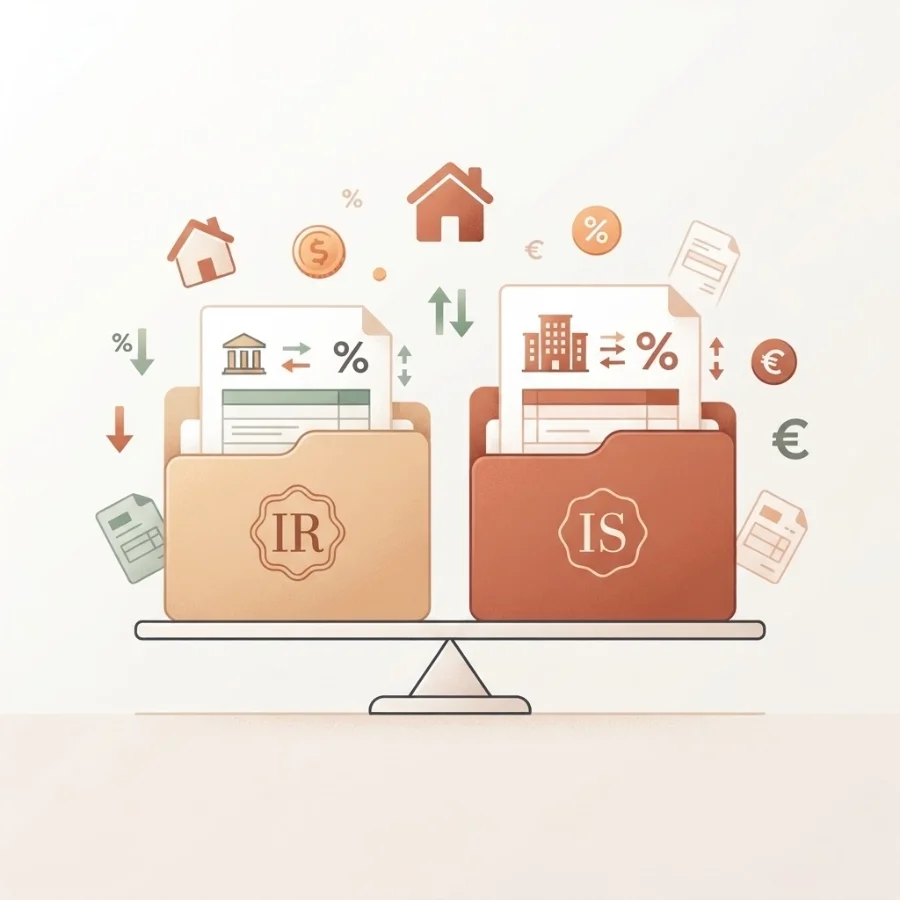
The SCI is an ownership tool, not a tax magic wand. The choice between income tax and corporate tax nonetheless has direct consequences for your financing and your cash flow.
The SCI, first and foremost a form of ownership
A property-holding company (SCI) makes it possible to buy and manage a property jointly, to organise its transmission and to separate assets. It does not, in itself, increase your borrowing capacity: the bank analyses the income and debt of the partners, who act as guarantors of the loan.
SCI subject to IR: transparency
Under income tax (IR) (the default regime), the company is “transparent”: rental income is taxed directly in the hands of the partners, at their marginal rate, plus social levies. Loan interest is deductible from the rent, but not the value of the property. This regime suits lightly taxed projects, long-term ownership and unfurnished lettings.
SCI subject to IS: depreciation
Under corporate tax (IS), the SCI is taxed on its profit (reduced rate of 15% up to €42,500 of profit, then 25%). Above all, it can depreciate the property: in accounting terms, this sharply reduces — or even cancels — taxable profit for many years, and improves available cash flow. The trade-off is paid on resale: the capital gain is calculated on the net book value, often heavier than under the regime for private individuals.
The concrete impact on financing
- Under IS, depreciation and deferred repayment improve cash flow — an argument in front of the bank, especially where the aim is to chain transactions.
- Under IR, the simplicity of management and the capital-gains tax regime for private individuals (allowances for length of ownership) may take precedence.
- The chosen structure (holding company, partner’s current account, guarantees) also influences the terms obtained.
There is no “good” regime in the absolute: the choice depends on your tax position, your time horizon and your wealth strategy. It is ideally decided with your chartered accountant, before signing.
This article sets out the broad principles and does not constitute personalised tax advice.
- IR: tax transparency, capital-gains tax for private individuals, suited to long-term ownership.
- IS: depreciation and better cash flow, but a heavier capital gain on resale.
- The SCI does not increase borrowing capacity: the partners act as guarantors.
- A trade-off to be confirmed with a chartered accountant.